Risk & Position Sizing
Build position sizes from drawdown math, realistic trading costs, and uncertainty in backtest results before applying Kelly.
- 01
 Mar 1, 2026#risk management
Loss-Profit Asymmetry: The Math That Kills Your Deposit
Why losing 50% requires 100% growth to recover, how volatility drag destroys capital even in sideways markets, and which formulas every algo trader must know for building risk management.
- 02
 Jul 23, 2026#slippage
Slippage curves, not slippage constants: cost models that survive contact with live trading
Replace constant-bps slippage with size, volatility and liquidity-dependent cost curves: the square-root law, fitting curves from TCA fills or public data, regime stress multipliers, and why your strategy leaderboard reshuffles.
- 03
 Mar 9, 2026#algo trading
Funding Rates Kill Your Leverage: Why PnL×50x Is a Fiction
How funding rates on Binance/Bybit turn beautiful high-leverage backtest results into guaranteed losses. Formulas, recalculation of real strategies, and the maximum leverage at which funding does not eat into profits.
- 04
 Mar 6, 2026#algotrading
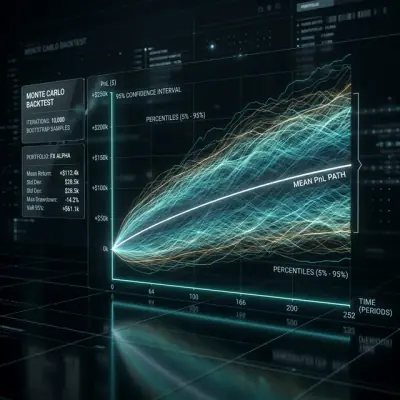
Monte Carlo Bootstrap: How to Get Confidence Intervals for a Backtest in 10 Lines of Code
Why a single-point estimate from a backtest is a dangerous illusion. How Monte Carlo bootstrap in 2 seconds of computation gives you a 95% confidence interval for PnL and MaxDD, and why this is a mandatory step before launching a strategy in production.
- 05
 Jun 23, 2026#risk management
The Kelly Criterion for Strategies: How to Size Positions and Allocate Capital
A strategy with positive expected value can still blow up your account if you get the bet size wrong. We walk through the Kelly criterion from deriving the formula to a portfolio of strategies: why full Kelly is dangerous, how fractional Kelly captures 75% of the growth at half the volatility, and an interactive calculator that shows how the Kelly fraction moves return and risk.